How Much Is Enough? Planning the Life You Want Before and After 50
"Enough" is rarely a number you can look up. A thoughtful look at how to define it for yourself — starting with the life you actually want, rather than the figure you think you should have.
There is a question that sits underneath most financial worry in midlife, and it is rarely asked directly. Not "how much do I have?" but "will it be enough?"
It is a difficult question because it seems to call for a single, authoritative number. And there are plenty of numbers offered — in headlines, in conversations with friends, in the confident rules of thumb that circulate online. Most of them are built for someone else's life.
Enough is not a figure you can look up. It is something you define. And the definition begins somewhere other than your bank balance.
Why the Question Feels So Hard
Part of the difficulty is that "enough" is usually treated as a target rather than a description. We imagine a number that, once reached, will make the uncertainty go away.
But uncertainty does not disappear at any figure. People with very substantial savings often worry about money just as much as those with modest ones. The anxiety is not always about the amount. It is about not knowing what the amount is for.
Without a clear picture of the life you are funding, no sum will ever feel quite sufficient. With one, a surprisingly modest sum can begin to feel secure.
Start With the Life, Not the Number
The most useful place to begin is not a spreadsheet but a description.
What does an ordinary week look like in the life you want after 50 — or after 60, or whenever work begins to recede? Where are you living? Who are you spending time with? What are you doing on a Tuesday morning?
It helps to think in three broad layers:
- The foundation — housing, food, utilities, council tax, insurance, transport. The costs of simply living well and safely
- The texture — the things that make life feel like yours: hobbies, travel, eating out, helping family, the occasional indulgence
- The cushion — room for the unexpected: a new boiler, a car that gives up, a period of care, a child who needs support
Each layer has a different character. The foundation needs to be reliable. The texture can flex. The cushion needs to exist, even if you hope never to use it.
Your Spending Will Change More Than You Expect
One of the most common assumptions is that later life will simply be today's life with less income. In practice, spending tends to change shape.
Commuting costs fade. Work clothes stop mattering. The mortgage may be paid off. But other things often grow — travel in the early, active years, home improvements once you are spending more time there, and later, perhaps, health and care.
A useful exercise is to look honestly at what you spend now and ask which of those costs belong to your working life and which belong to you. Many people find the second list is shorter than they feared. Some find it is longer.
Either way, the answer is more useful than a guess.
Where the Income Might Come From
Once you have a sense of what the life might cost, the next step is understanding what might fund it.
For most people in the UK, that means some combination of the State Pension, workplace and personal pensions, ISAs and other savings, and perhaps property. For some it also includes part-time or flexible work, which many people now choose for reasons that have as much to do with purpose as income.
It is worth requesting your State Pension forecast and gathering your pension statements in one place. Seeing everything together often changes the picture — sometimes reassuringly, sometimes not. Both are worth knowing.
Turning those pots into a dependable income is where things become genuinely complicated. The choices around how and when to draw on pensions, how much risk to keep, and how to handle tax are significant, and they are difficult to reverse. This is where a conversation with a regulated financial adviser is most valuable.
The Quiet Value of Deciding
There is a particular kind of freedom in deciding what enough means to you.
It allows you to stop measuring yourself against other people's numbers. It makes it easier to say yes to something now without the background hum of guilt. And it gives you a way of noticing when you have arrived — rather than continuing to chase a target that keeps moving.
Enough is not the same as everything. It is the point at which more money would change very little about the life you actually want to live.
For some people, that point is closer than they think.
Reflection Questions
- If I described an ordinary week in the life I want, what would it include?
- Which of my current costs belong to my working life, and which belong to me?
- Have I ever brought all my pensions, savings and State Pension forecast together in one place?
- Whose idea of "enough" have I been measuring myself against?
- At what point would more money stop making a meaningful difference to my life?
Final Thoughts
The question of enough is not really a financial question at first. It is a question about what you value, and what kind of life you want to protect.
The numbers matter, and they deserve care and good advice. But they work best when they serve a picture you have drawn yourself.
Define the life first. The number tends to follow.
You might also find useful
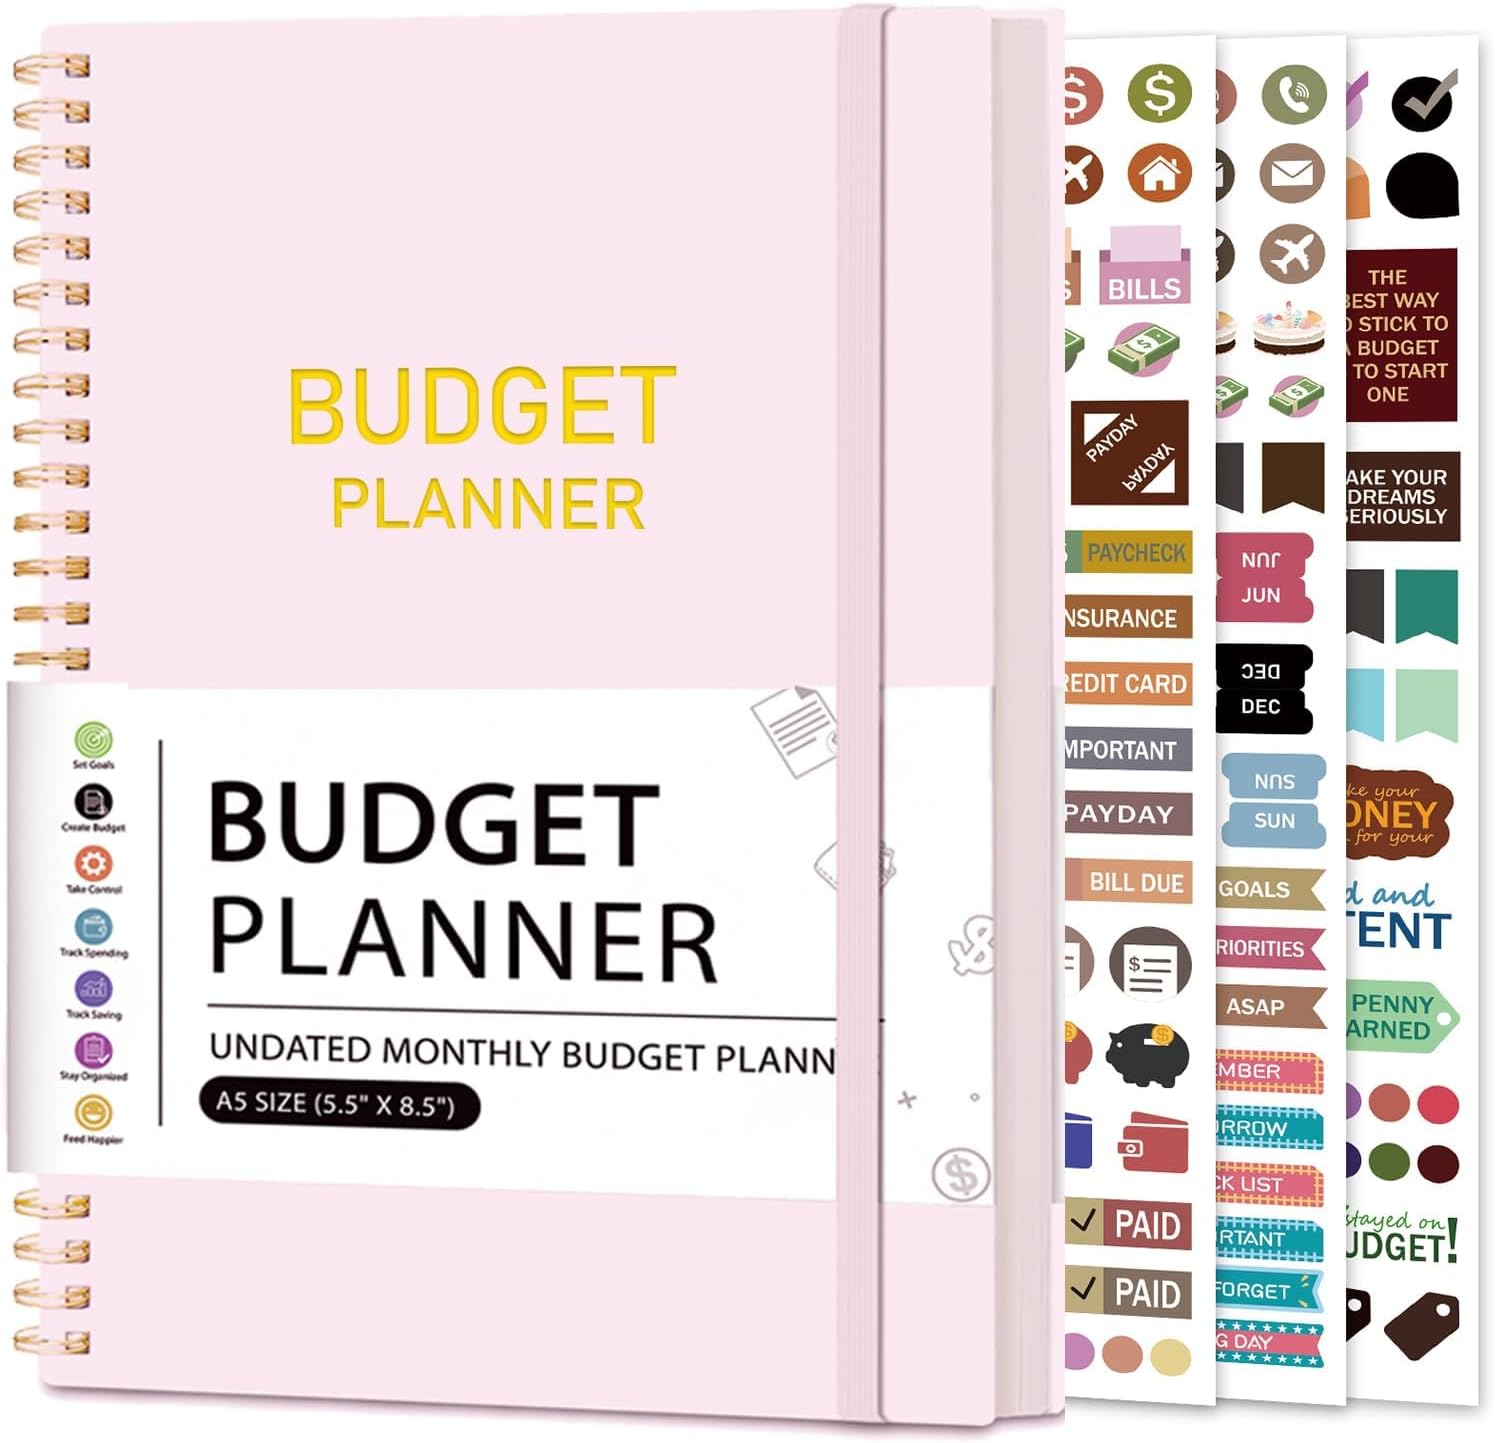
Budget Planner Monthly Financial Organizer
A structured monthly planner to track income, expenses and savings — helping you build a clear picture of your financial position.
View on Amazon → (opens in a new tab)
JUNDUN Fireproof Document Storage Box
Keep your important financial and legal documents safe with this fireproof and waterproof storage box.
View on Amazon → (opens in a new tab)As an Amazon Associate I earn from qualifying purchases.